Caregiving Households Were More Than Twice as Likely to Tap Retirement Savings.
A Nov. 16 Pew Charitable Trusts brief found 19% of caregiving households had withdrawn retirement money, versus 8% of other households. Every respondent worked without a workplace retirement plan. Shorter hours and care bills help explain why the nest egg gets tapped.
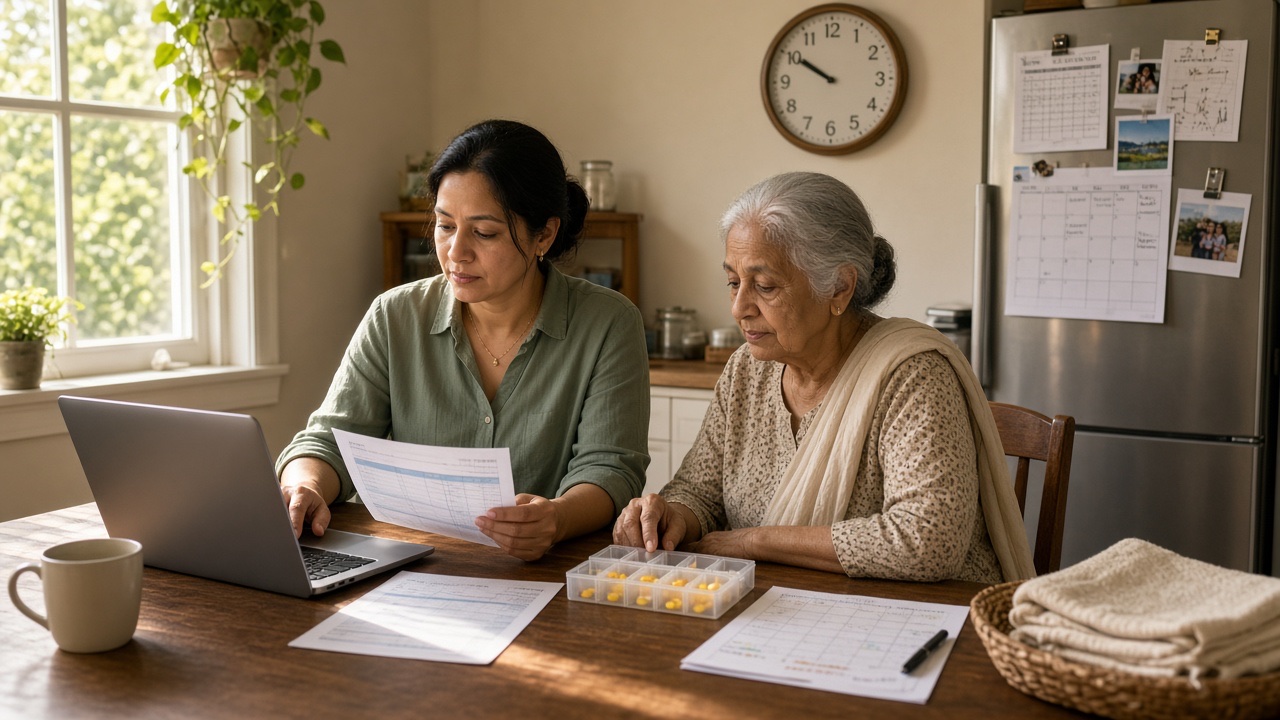
On Nov. 16 The Pew Charitable Trusts, the Philadelphia nonprofit that studies retirement access and household finance, published a brief that puts a hard number on caregiving’s money pressure. Among working people who had no retirement plan at their job, 19% of caregiving households said they had taken money from a retirement account in the prior year. Only 8% of households without caregiving said the same. That is more than twice the rate.
Keep the sample in view. Every person in this survey already lacked a workplace 401(k), 403(b), or similar plan. Pew fielded the questionnaire in 2024 among 1,122 workers ages 18 to 64. The findings are built for Black, White, and Hispanic workers in that uncovered group. The Trusts could not reach enough Asian American and Pacific Islander respondents to include them in the published dataset, so these percentages map uncovered workers. They are not a full portrait of every diaspora household.
Caregiving here means unpaid help for an adult. Someone in the household helped a relative or friend 18 or older with personal needs, chores, money management, or outside services in the last 12 months. One in four respondents lived in a caregiving household. Nearly three in four of those care situations involved someone 50 or older. Child care was not counted.
Shorter schedules show up right away. Caregiving workers were far more likely to work part time: 55%, compared with 34% of workers who were not caregiving. Only 45% of caregiving workers held full-time jobs, against 66% of the others. A shorter week shrinks the paycheck that covers grocery runs, rides to appointments, and the cash buffer that keeps an IRA untouched. The federal Family and Medical Leave Act can protect a job at covered employers, but the leave is unpaid. Pay still falls when hours do.
The bills arrive on the same calendar. Thirty-four percent of caregiving households said care costs made it harder to hit their financial goals; another 9% were not sure. AARP’s 2026 out-of-pocket study, separate from Pew, put average family-caregiver spending near $11,508 a year, about 31% of household income in that sample. In Pew’s survey the pressure showed up as skipped bills (31% versus 17%), a declined debit or credit card (28% versus 13%), a postponed prescription (24% versus 11%), and a payday or personal loan (22% versus 12%). When checking is already thin, a retirement balance from a prior job or an IRA is often the nearest cash.
Financial stress actions in the prior 12 months
Share of households in Pew’s 2024 survey of workers without a workplace retirement plan. Caregiving households reported each action more often.
| Action | Caregiving household | Other household |
|---|---|---|
| Took money from a retirement account | 19% | 8% |
| Skipped a bill (not rent/mortgage) | 31% | 17% |
| Card declined for insufficient funds | 28% | 13% |
| Skipped or postponed a prescription | 24% | 11% |
| Took a payday, personal, or other loan | 22% | 12% |
| Rated household finances as poor | 20% | 11% |
| Rarely or never had money left at month-end | 45% | 30% |
What disappears more quietly is the money that never goes in. Cut hours and you cut the dollars you would have put into any account you fund yourself. Among people who do have a workplace plan, the Employee Benefit Research Institute’s 2026 Retirement Confidence Survey found 54% of caregiving workers saying care hurt the hours they could work, and 19% saying they reduced retirement-plan contributions. AARP’s November modeling of caregivers born in the early 1980s put average lifetime losses near $120,500, mostly from lower earnings, with smaller pieces from workplace retirement income and future Social Security. You will not see that shortfall on a receipt. You will see it later in a smaller nest egg.
Desire to save was not the divide. Large shares of both groups said building wealth mattered and that they would join an employer plan or a state auto-IRA if one appeared. Caregivers did answer differently on one point: 65% said a matching contribution would make them much more likely to participate, versus 52% of noncaregivers. Starting in tax year 2027 the federal Saver’s Match, created under the SECURE 2.0 retirement law, can deposit a 50% government match into an eligible retirement account for lower- and moderate-income savers, up to $1,000 for a single filer and $2,000 on a joint return at the full rate. State payroll IRA programs already cover more than a million workers whose employers offer no plan. A match does not restore cut hours. For uncovered workers it can still decide whether a first deposit ever happens.
For a household that also wires money to parents abroad or shares a multigenerational roof, the same month can hold a care bill, a remittance, and a thinner retirement line. Line the care cash and the standing family transfer up against any IRA contribution in the Family Support Budget Calculator and the Parent Care Cost Planner. Caregiver Costs and Retirement Delay Benchmarks for Employed Adult Children and How to Plan Remittances Without Derailing Retirement help keep those lines honest. If nobody at work offers a plan, start with Retirement Planning When Your Parents Did Not Have a 401(k). Our earlier EBRI story on lost compounding is Family Caregivers Aren’t Only Spending Money. They’re Losing Years of Retirement Savings.
Before you cut hours or pull from an IRA, jot the current schedule, take-home pay, and what retirement loses when pay falls. Early withdrawals can face income tax and, before age 59½, often an extra 10% tax unless an exception fits. Ask HR, in writing, what happens to benefits and any plan eligibility if the week drops below full time. Make the call with the full month in view, not only the crisis in front of you.
This is educational reporting on published survey findings, not financial, tax, or benefits advice. Confirm your own plan rules, tax situation, and leave rights before you change hours or take a distribution.
Related content
Further diaspora reading
- Family Caregivers Aren’t Only Spending Money. They’re Losing Years of Retirement Savings (Generational)
- Caregiver Costs and Retirement Delay Benchmarks for Employed Adult Children (Generational)
- How to Plan Remittances Without Derailing Retirement (Generational)
- Highs and Lows of Asian Multi-Generational Living (Goldsea)
- Americans fear running out of money more than dying. (Generational)
Generational Take
Get the next Generational Take
Get our latest practical tips and takes in your inbox. No spam.