Parents Abroad Are Gifting $115,000 Toward a House. Save These Papers Before the Wire.
A U.S. buyer’s overseas down-payment gift needs a gift letter and a wire trail for the lender. When related foreign gifts top $100,000 in a year, Form 3520 Part IV usually joins the calendar.
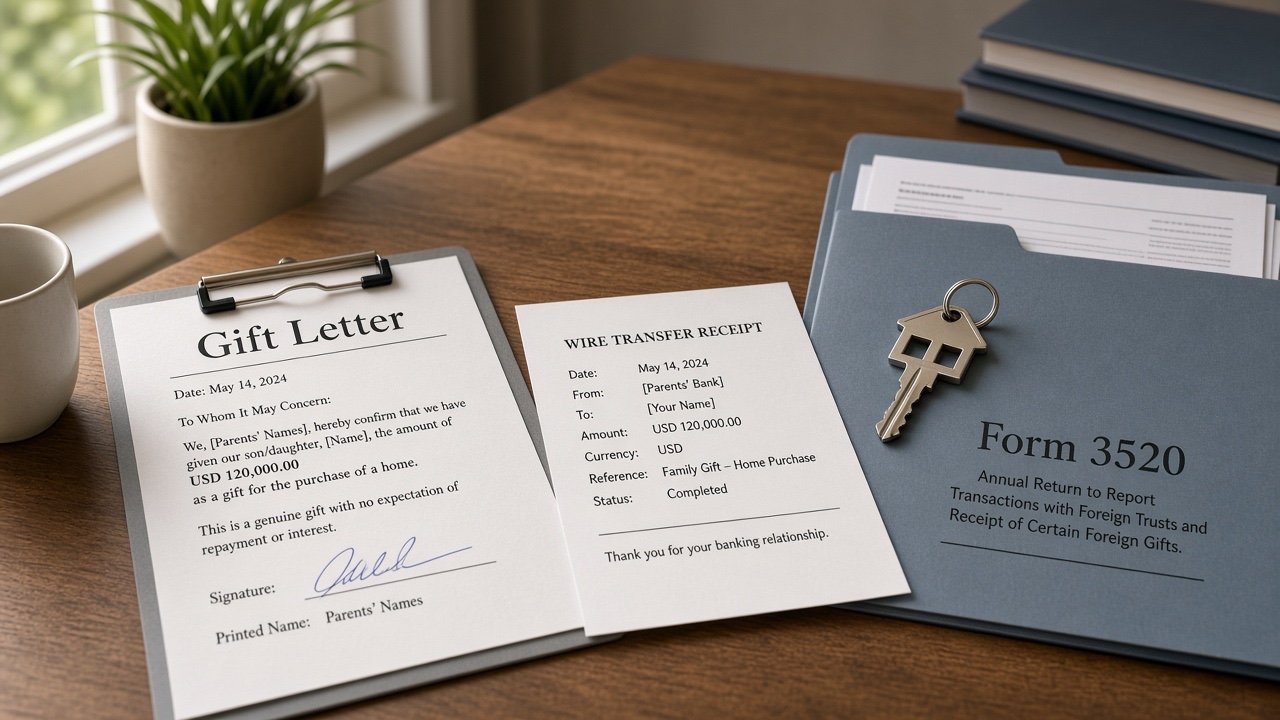
Parents abroad offer a large gift so you can close on a U.S. house. That help is common in diaspora purchases. A National Association of Realtors survey of 2022 buyers found 22% of Asian and Pacific Islander purchasers used a gift from a relative or friend toward the down payment, well above the share for White buyers. When the money crosses an ocean, you are juggling two timelines: the lender’s document list before closing, and Form 3520 if foreign gifts in the same year climb past the IRS reporting line.
Here is a concrete year. You are a U.S. person buying a primary home in 2026. Your mother, a nonresident alien, wires $90,000 in March straight to escrow for the down payment. Your father, also a nonresident alien and related to her, wires another $25,000 in October for closing costs and furniture. Neither transfer alone creates a U.S. income-tax bill. Together they are $115,000 of gifts from related foreign individuals in one tax year.
Paper trail for one overseas down-payment gift
Sample calendar-year 2026 file for a U.S. buyer. Your lender may ask for a slightly different pack. Confirm before anyone sends money.
| Document | What it is for | When to gather it |
|---|---|---|
| Signed gift letter | Amount, donor identity, relationship, and a clear no-repayment statement | Before the wire; use the lender’s template if they have one |
| Donor bank statements | Shows the money was available to gift | With English translations if the pages are not in English |
| Wire or SWIFT confirmation | Shows funds left the donor account | Save the day the transfer posts |
| Your deposit or escrow receipt | Shows the same dollars arrived | Match the gift-letter amount after fees when you can |
| Form 3520 Part IV (if thresholds hit) | Reports large foreign gifts; not a tax bill by itself | After closing, on the tax-year calendar, usually with your April filing |
Form 3520 Part IV: amounts, aggregation, deadlines
From IRS Instructions for Form 3520 (revised December 2025) and the IRS Gifts from foreign person page. Educational only; confirm with a tax professional.
| Rule | What the IRS instructions say |
|---|---|
| Individual / estate threshold | Report if you received more than $100,000 in aggregate gifts or bequests from a nonresident alien or foreign estate in the tax year |
| Aggregation | Combine gifts from foreign persons you know or have reason to know are related, or when one acts as a nominee or intermediary |
| Related-donor example | A $75,000 gift and a $40,000 gift from related nonresident aliens both go on the return once the combined total exceeds $100,000 |
| Detail lines | Once over $100,000, separately identify each gift over $5,000 |
| Foreign entity gifts | Purported gifts from foreign corporations or partnerships use a lower inflation-adjusted threshold ($20,573 for 2026) |
| Deadline (calendar-year filer) | Generally April 15 after the tax year; June 15 if you live and work abroad; up to October 15 with a timely income-tax extension. A discretionary December income-tax extension does not push Form 3520 past October 15 |
| How to file | Mail Form 3520 separately to the Ogden IRS campus. Do not staple it to Form 1040. If you filed Form 4868, check box 1k on Form 3520 |
| Late or incomplete filing | Section 6039F can assess 5% of the gift per month, capped at 25%, unless reasonable cause applies |
Source: IRS Instructions for Form 3520 (12/2025); IRS Gifts from foreign person
The lender still wants a gift letter before those wires leave. Fannie Mae’s Selling Guide B3-4.3-04 asks for the donor’s name, address, telephone number, and relationship to you, the gift amount, and a written statement that no repayment is expected. Freddie Mac and FHA’s Handbook 4000.1 ask for the same core points. If anyone still expects you to “pay it back when you can,” settle that before money moves. A repayable transfer can look like debt under ability-to-repay rules even when it never hits a credit report.
Save the trail that proves the money moved. Keep donor bank statements showing the funds were there, English translations if the pages are not in English, the wire or SWIFT confirmation showing the money left that account, and your deposit slip or escrow receipt showing the same dollars arrived. Fannie Mae accepts evidence of an electronic transfer from the donor’s account to you or to the closing agent. For a large overseas gift, many loan officers prefer a direct wire to escrow so the cash never mixes with rent and remittances on your checking statement. Call title or escrow on a number you already trust before parents send. Last-minute emailed changes to wiring instructions are a known closing scam.
Form 3520 is the April pile, not the closing pile. Its full name is Annual Return to Report Transactions With Foreign Trusts and Receipt of Certain Foreign Gifts. Part IV is the section U.S. persons use for certain large foreign gifts. IRS instructions say you generally file when you received more than $100,000 in gifts or bequests in the year from a nonresident alien or a foreign estate, counting related foreign persons you know or have reason to know are related, and counting nominees or intermediaries. The instructions give a pair of related nonresident aliens who gift $75,000 and $40,000. Once the combined total clears $100,000, both gifts go on the return, and each gift over $5,000 gets its own detail line.
In the $90,000-plus-$25,000 year, both wires belong on Form 3520. Reporting the gift is not the same as owing income tax on it. Skipping or late-filing Part IV still has teeth. Under section 6039F, the IRS may decide the income-tax consequences of the receipt and can assess 5% of the gift for each month the failure continues, capped at 25%, unless you show reasonable cause. Mail the form to the Ogden campus. Do not attach it to Form 1040. For a calendar-year filer, the due date is generally April 15 after the tax year. If you live and work outside the United States, it is generally June 15. A timely Form 4868 income-tax extension can carry Form 3520 to October 15. Check box 1k on Form 3520 when you use that extension. A later discretionary December extension for the income return does not move Form 3520 past October 15.
Form 709 is a different form for a different person. U.S. donors often file it when gifts to one recipient exceed the annual exclusion, $19,000 per person in 2026 on the IRS gift-tax FAQ. Overseas parents who are nonresident aliens usually sit on a different donor-side path. Your job as the U.S. recipient is the Part IV threshold, the related-donor math, and the Ogden mailing. Purported gifts from a foreign corporation or partnership use a lower threshold, $20,573 for 2026, and the IRS may recharacterize those transfers.
Ask your loan officer for the gift-letter template and preferred wire path before parents book the remittance. Ask a cross-border tax professional whether this year’s gifts, including smaller “furniture” wires from related relatives, cross $100,000. Parent Down-Payment Gift Playbook That Closes Clean and Gift Down Payment and Lender Paperwork for Diaspora Buyers cover the closing documents. Parent Gift and Family Transfer Tax Paperwork for Diaspora Households keeps Form 709 and Form 3520 from getting mixed up. Price the house with the gift in cash-to-close and the remittance line still active in the First Home Affordability Calculator.
After you get the keys, keep the gift letter, donor statements, wire confirmations, and escrow receipt in one folder. If foreign gifts from related donors cleared $100,000 that year, put Form 3520 on the April calendar the same week the Closing Disclosure lands. Closing day ends the mortgage scramble. It does not end the reporting file.
This is educational reporting on lender documentation and IRS Form 3520 instructions, not tax, legal, or mortgage advice. Thresholds, loan programs, and lender overlays change. Confirm your facts with your loan officer and a qualified tax professional before money moves.
Related content
Further diaspora reading
- Parent Down-Payment Gift Playbook That Closes Clean (Generational)
- Gift Down Payment and Lender Paperwork for Diaspora Buyers (Generational)
- Parent Gift and Family Transfer Tax Paperwork for Diaspora Households (Generational)
- Asians Earn Most but Fall Most in Home Ownership (Goldsea)
- Mortgage Readiness Benchmarks with a Family Support Line (Generational)
Generational Take
Get the next Generational Take
Get our latest practical tips and takes in your inbox. No spam.