Shopee’s parent is becoming a much bigger lender. Meet Monee.
Sea’s third-quarter results put Monee’s consumer and small-business lending in focus: $1.6 billion in revenue, a $12.6 billion loan book, and credit-loss provisions up 82%. Checkout “pay later” is a balance-sheet business. The loan balances show how fast the book is growing. The delinquency and provision lines show what that growth costs.
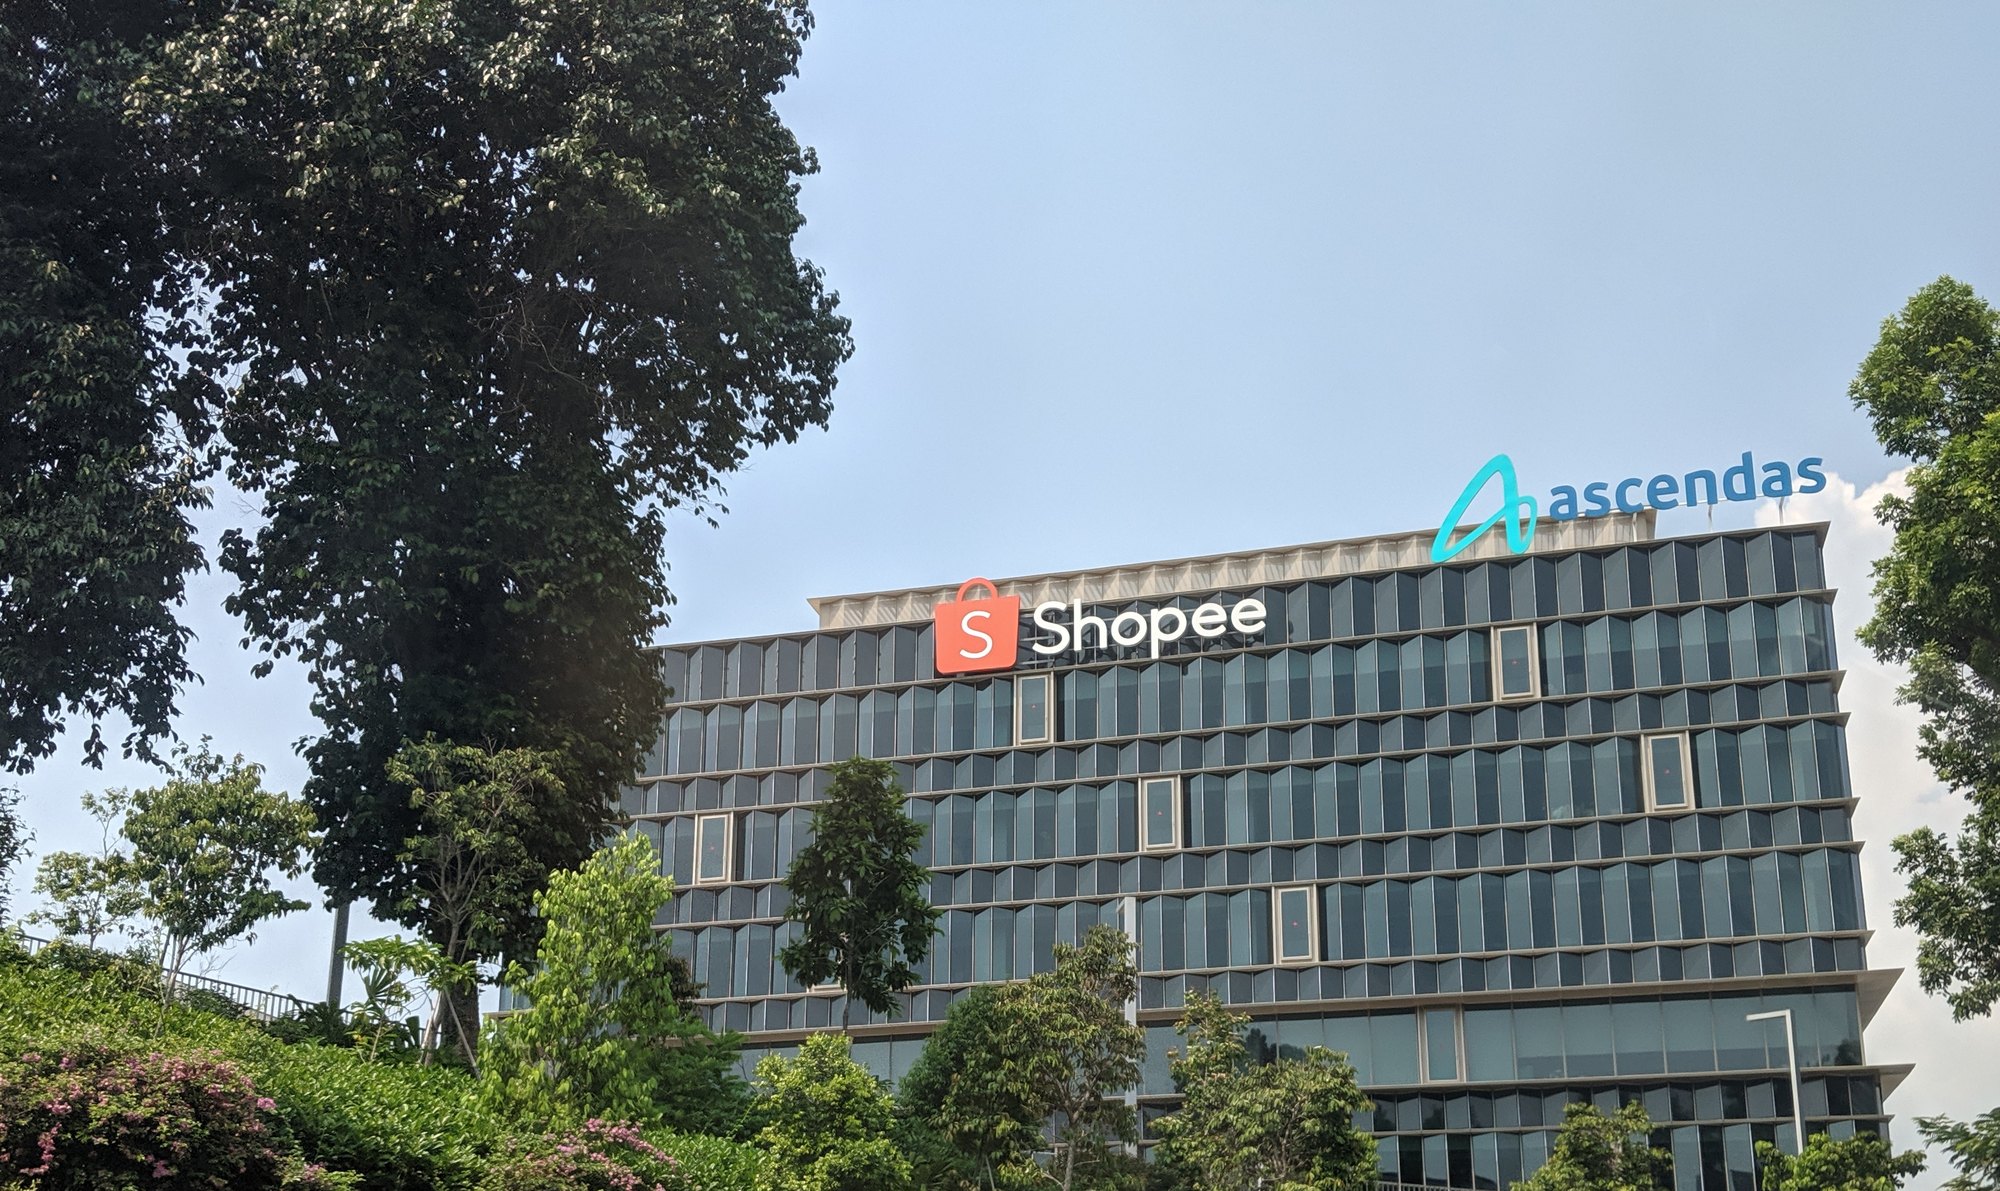
Sea Limited reported third-quarter results on November 10, and Shopee again carried the headlines: group revenue of $8.6 billion, up 43%, and net income of $502.5 million, up 34%. Look one segment over. Monee, Sea’s digital financial services arm, posted $1.6 billion in revenue, up 64% from a year earlier. Most of that came from lending to shoppers and small businesses. Consumer and SME loans outstanding hit $12.6 billion, up 60%. Monee’s adjusted EBITDA rose only 16%, to $298.3 million. Balances grew a lot faster than the profit left after costs.
Sea is the Singapore company behind Shopee and the Free Fire publisher Garena. In May 2025 it renamed its fintech unit from SeaMoney to Monee. The product many Shopee buyers already know is SPayLater: take the goods now, pay next month or in installments. The merchant gets paid up front. Monee, or a partner bank on its platform, holds the credit risk. Purchase history and app behavior help decide who gets a limit. What used to end as a wallet tap can open as a loan. Chairman and chief executive Forrest Li told investors Monee is putting that credit into more everyday spending, both inside Shopee and outside it.
A lender’s income is mostly interest and fees on money already out the door. Sea said Monee’s revenue and operating income come primarily from consumer and SME credit. Of the $12.6 billion outstanding at September 30, $11.2 billion sat on Sea’s books. Another $1.3 billion was off-book, mainly loans other financial institutions make through Monee’s channeling arrangements. Someone still has to fund those loans. Monee’s cost of revenue rose 44% to $180.8 million, from higher interest on deposits, payment-network costs in banking, funding costs, collection expenses, and transaction fees in credit. Bigger book, bigger interest check, bigger bill to keep the money flowing.
If you have used Affirm or Klarna at a U.S. checkout, the stress lines will look familiar. Loans past due more than ninety days were 1.3% of the consumer and SME book, up from 1.1% a year earlier. The share is still small, and it moved. On the earnings call, management pointed to softer credit conditions in Thailand and Brazil, plus a mix that is tilting toward Brazil and toward SPayLater used away from Shopee. That off-Shopee SPayLater book more than doubled year on year and was nearly a quarter of all SPayLater by September. In Malaysia it was closer to 40%. Cash loans and off-Shopee credit together were about half of everything outstanding. Plenty of the lending now happens after the Shopee cart is closed.
Provisions climbed faster than the delinquency rate. Sea’s provision for credit losses jumped 82% to $681.5 million from $373.8 million a year earlier. That is the charge a lender takes when it books expected losses as new loans go out. A young book can still print a tidy ninety-day ratio while provisions rise, because many first-time borrowers have not finished a full repayment cycle yet. Management said it tightened underwriting and credit limits for some segments when conditions softened. Active credit users reached nearly 44 million, up about 28%, after almost 6 million first-time borrowers in the quarter. Average loan outstanding per user rose 23%. More than 40% of active credit users held two or more Monee credit products. A second product grows the balance. It also means one rough month can hit more than one payment on the same phone.
Li also sketched a longer plan. He called Monee one of the largest unsecured consumer lenders in Southeast Asia, by Sea’s own measure, and said the company hopes to list Monee on its own in the next one to three years if markets and regulators allow. Shopee would remain a partner. For anyone holding SE stock, that is a corporate-structure question. For families whose relatives sell or shop on Shopee in Indonesia, the Philippines, Vietnam, Thailand, Malaysia, or Brazil, it is a simpler reminder: the orange bag sits next to a lender that also runs wallets, digital banks, cash loans, and pay-later that works offline, including a Mastercard-linked SPayLater card in Thailand.
Treat the quarter like a sibling’s installment calendar. The revenue and loan balances say people are using the product. The slower profit growth, the higher ninety-day rate, and the jump in provisions say the bill for that growth is rising. Affirm’s card spending more than doubled. Buy now, pay later is leaving the checkout button. is the U.S. cousin of the same habit walking off the merchant page. Debt Payoff Priority Benchmarks with Family Support Obligations and Credit and Family Money Myths for Immigrant Households help sort what already sits next to rent and remittances. Keep a buffer with Emergency Fund Benchmarks When Family Depends on You and the Family Support Budget Calculator. If SE is in a brokerage account, size it with Taxable Investing Basics for First-Gen Professionals.
More time at checkout is still a loan. Monee’s filing just names the lender.
Related content
Further diaspora reading
- Affirm’s card spending more than doubled. Buy now, pay later is leaving the checkout button. (Generational)
- Debt Payoff Priority Benchmarks with Family Support Obligations (Generational)
- Credit and Family Money Myths for Immigrant Households (Generational)
- Thanksgiving Shopping Spree Surpassed Expectations (Goldsea)
- Lillian Zhang Gives Gen Z a Blueprint for Building Wealth (Goldsea)
Generational Take
Get the next Generational Take
Get our latest practical tips and takes in your inbox. No spam.