Korean American shop owners used to outnumber office workers. New stores under two years old fell to 8%.
A Korea Daily and Bank of Hope survey of about 5,050 people finds salaried jobs now lead the shop almost two to one. The house is carrying more of the wealth file than the register.
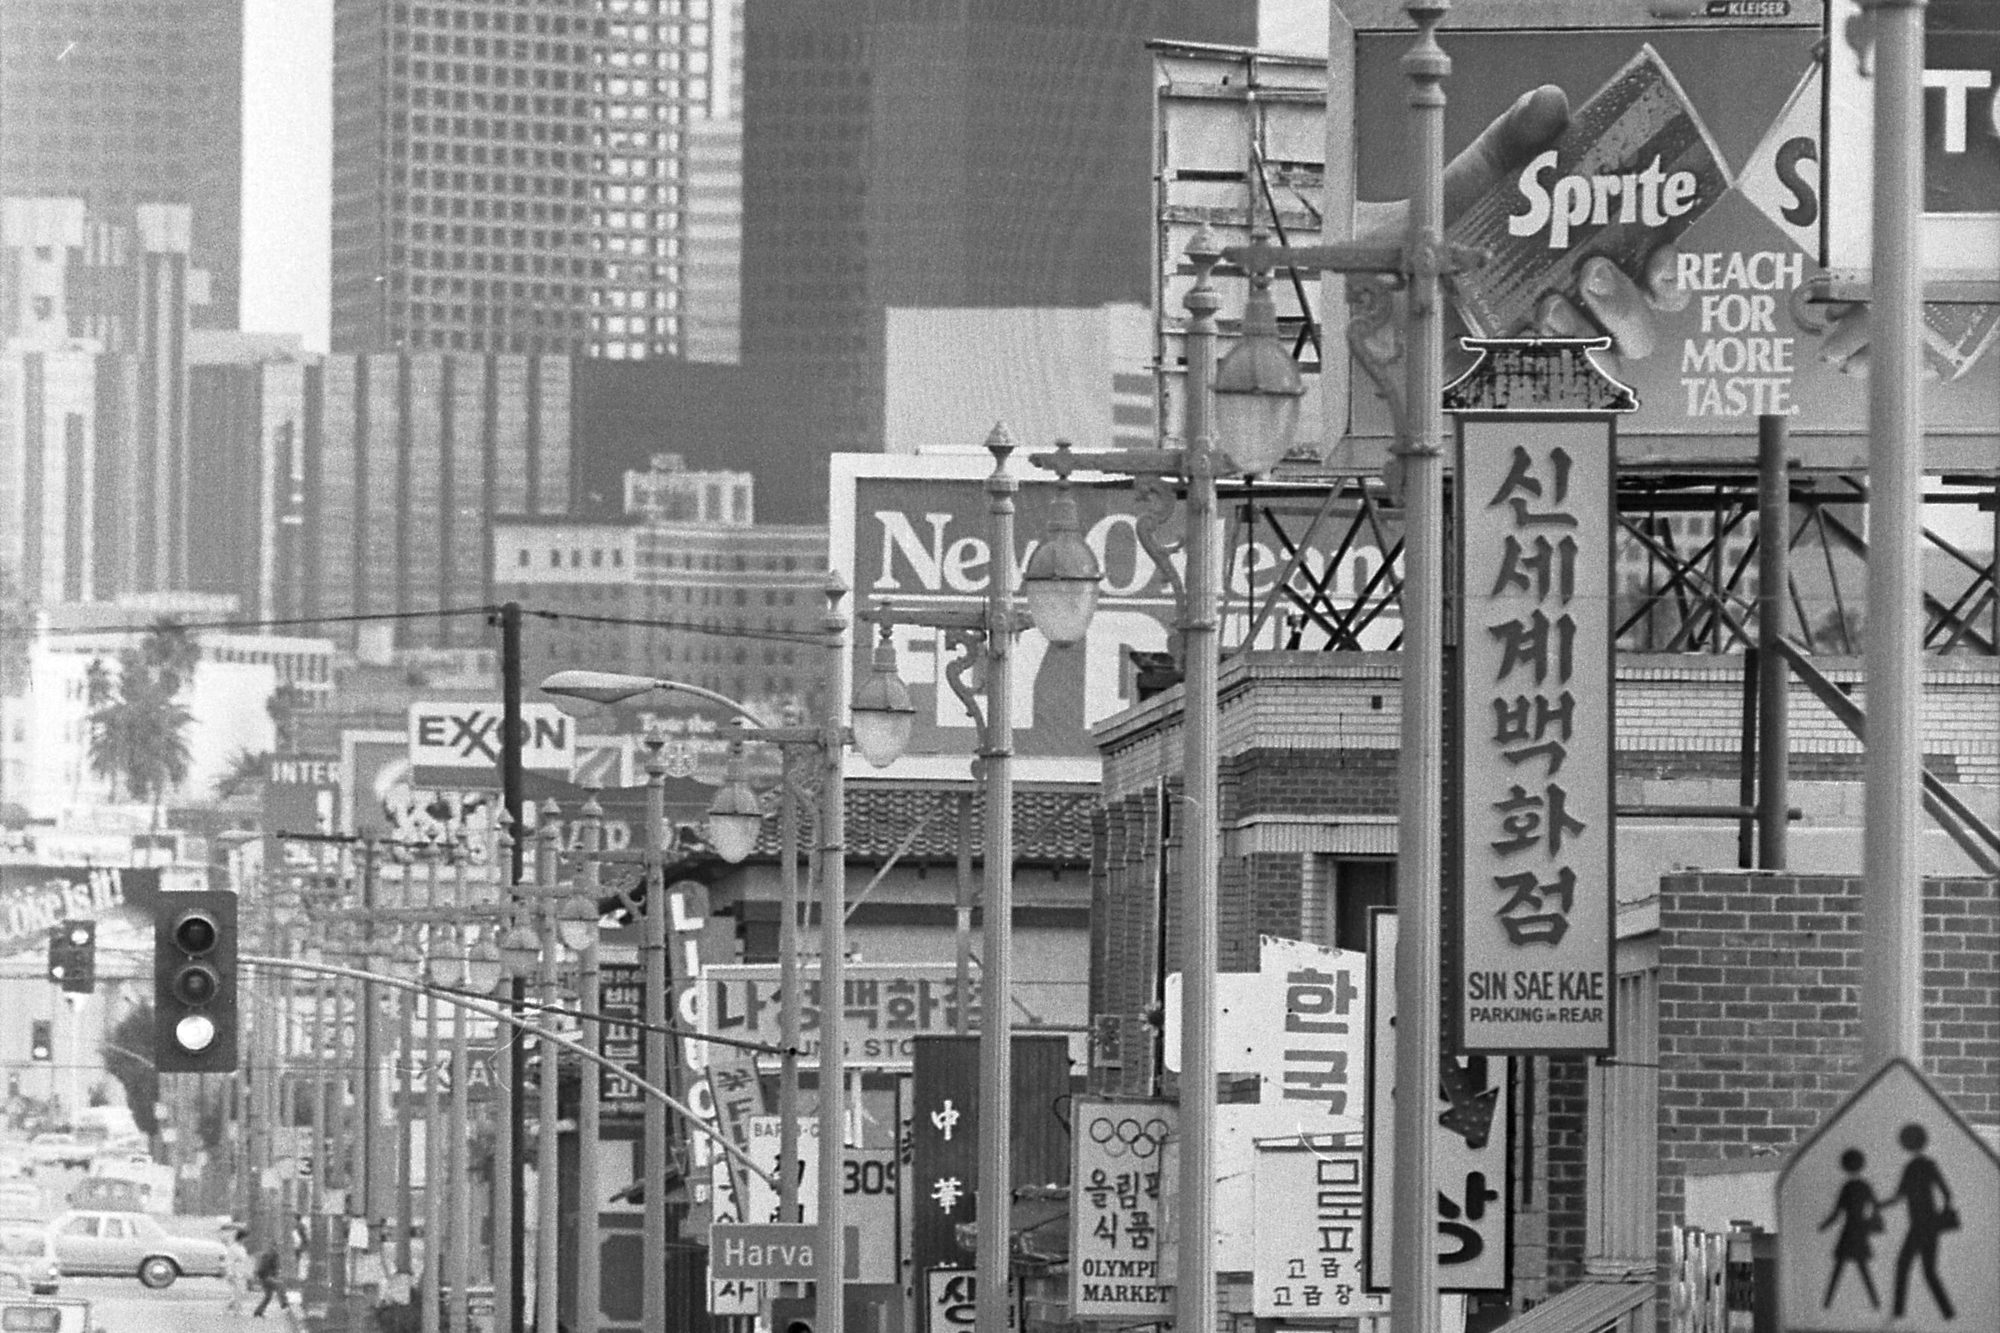
In 2020, Korean American shop owners still outnumbered office workers in The Korea Daily's economic survey. This year the office won. Self-employed owners were 17.6 percent of respondents. Salaried workers were 33.3 percent, almost two to one.
New businesses open less than two years fell from 39.4 percent of shops in 2020 to 8.0 percent. A lot of families still talk as if the next generation will take the register. More of them took a salaried job. Fewer of them are signing a new lease.
Self-employment slid from 24.4 percent in 2020 to 19.6 percent in 2023 and 17.6 percent now. Salaried work jumped from 22.9 percent to 35.3 percent, then eased to 33.3 percent. Retirees rose from 11.9 percent to 21.0 percent. The kids left the Saturday shift. The parents aged out of it.
The shops that remain are getting squeezed. Among business respondents, 57.1 percent said sales fell from last year. Only 10.5 percent saw a rise. Almost half named weaker foot traffic as the single biggest problem. More than a third named costs and commercial rent, a worry that climbed from 15.3 percent in 2020 to 35.8 percent. Nine in ten of those businesses employ 10 people or fewer.
You can see the missing customers in the household answers. Some 76.4 percent said inflation made finances worse this year, up from 70.7 percent in 2023. Groceries were the top burden for 59.4 percent. About one in four respondents cut how much they buy. Another quarter cut dining out.
That is how a restaurant or a gift shop loses the Saturday. About one in six people now works a side gig, often rideshare. It covers the cart. It does not refill a down payment.
The Korea Daily is the U.S. edition of JoongAng Ilbo, the Seoul newspaper. With Bank of Hope, the largest Korean American bank, it ran this third edition online from April 27 to May 25. About 5,051 people filled out a short form on the paper's site and were entered in a prize drawing. It is a big reader sample, not a government survey. The three-year trend is the part that holds.
Pew Research Center, using the Census Bureau's American Community Survey, counted about 1.83 million people who identify as Korean alone or in combination as of 2023. The median Korean-headed household earned $93,600 that year. More than half of this newspaper sample put annual income under $70,000. That is what a reader survey with a large retired share looks like.
For a family still on the lease, the next question is who actually wants the keys. Succession and Exit Planning for Immigrant-Owned Family Shops is the paperwork if the kids already have health insurance and a workplace 401(k). Opening another two-year shop because the 2020 cohort did is the expensive answer.
The house is picking up the wealth work the register used to do. Homeownership in the survey rose to 57.6 percent, from 50.7 percent in 2020. Pew's Census read is close: 55 percent of Korean-headed households own. Among this survey's owners, 35.4 percent now put the house at $1 million or more, up from 14.0 percent in 2020. Those are the same roofs getting marked up.
People in their 30s are the exception. Only 45.9 percent of that age group own, the one bracket where renters are still the majority. More than one in five renters now pay $3,000 a month or more. The parents who bought earlier are sitting on equity. The kids who stayed in the apartment are paying the entry tax.
The salaried path shows up in the brokerage too. Respondents with no investments fell from 42.4 percent in 2020 to 15.9 percent. Individual retirement accounts, the tax-deferred accounts you open yourself, were the top retirement vehicle at 22.6 percent, ahead of 401(k) workplace plans at 18.0 percent. About two-thirds of professionals and corporate employees said they are preparing for retirement. Freelancers and service workers sat closer to half. More than half of investors still said safety mattered more than yield.
Bank of Hope sponsored the survey and still lost the everyday account. Bank of America was the primary bank for 23.5 percent of respondents, Chase for 22.8 percent. Hope had 18.4 percent. Hanmi Bank, the first Korean American bank, founded in 1982, had 8.9 percent.
The kids who took the office job bank where the ATM is. They still walk into a Korean desk when the paperwork has to happen in Korean. Trust in those community banks is high. Satisfaction with small-business loans is 20.6 percent positive and 27.3 percent negative.
If the family still has a shop, write down who owns it and what a sale would actually clear before the next rent cycle. If the kids already have a salary, fund the IRA the way an earlier generation funded the inventory.
This is educational reporting on a newspaper survey, not investment, tax, or legal advice. Shares describe this sample, not every Korean American household.
Related content
Further diaspora reading
- Succession and Exit Planning for Immigrant-Owned Family Shops (Generational)
- Immigrant-Owned Small Business Financing Basics (Generational)
- Tina Lee takes T&T into California. San Jose's first week beat every Loblaw opening. (Generational)
- How to Build Generational Wealth as a Child of Immigrants (Generational)
- Asian-Owned Coffee Shops Brewing Community In LA (Goldsea)
Generational Take
Get the next Generational Take
Get our latest practical tips and takes in your inbox. No spam.